Thailand's condo oversupply in 2026: 220,000 unsold homes and a loan market that won't open
AI-assisted writing and charts | Reviewed by YYao | Data as of 14 October 2026 | ThaiHomeRB. Every figure names its source; where sources disagree, both are shown.
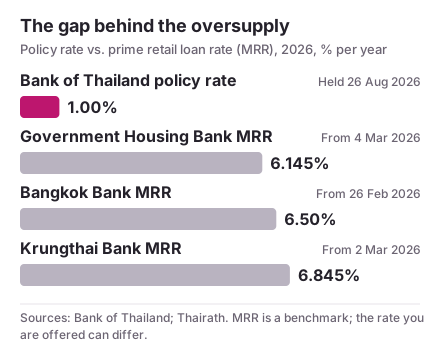
The Bank of Thailand's policy rate is 1.00%. Bangkok Bank's prime retail loan rate is 6.50%. In the gap between those two numbers sit more than 220,000 unsold homes, and a mortgage market where, developers report, 40–45% of applications were turned down in 2024–25.
The short answer
- The stock: roughly 220,000–350,000 unsold homes, depending on who counts. Clearing it will take years.
- The buyers: foreign demand is changing nationality, not growing. Local buyers are held back by credit.
- The rates: the policy rate fell to 1.00%, but bank loan rates are still about 6–7%.
- For buyers: analysts expect a buyer's market for one to two years.
- Not covered: we found no reliable rent data, so we make no claim about rents.
How big is the oversupply?
There is no single official number. Estimates run from about 220,000 to 400,000 homes.
- 221,805 unsold homes nationwide (AREA, Feb 2026), about 50 months to clear. Pattaya Mail
- ~350,000 unsold Bangkok condos (Knight Frank, Q1 2026). At about 60,000 transfers a year, that is 5–6 years. Knight Frank
- ~220,000 in Bangkok and possibly 400,000 nationwide (AREA's Sopon Pornchokchai, Jan 2026). The Nation
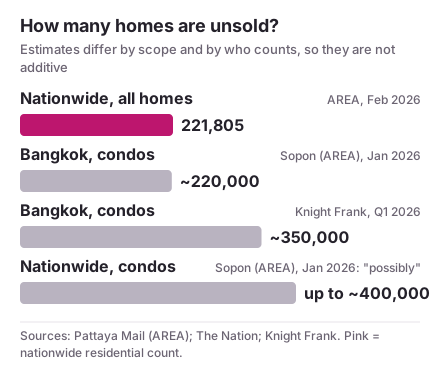
Differences in scope (condos only or all homes, finished or under construction) likely explain the gap. We could not confirm this.
Is more supply still coming?
Less than before, but not none.
- Q1 2026: about 6,174 new Bangkok condos, none in the CBD, up to 68% below THB 80,000 per sqm. Most target buyers with THB 1.5–3 million. Knight Frank
- Q2 2026: 2,332 units, down 67% on Q1. First half: 9,501 units, up 42% year on year. Full-year forecast: 17,000–20,000. Cushman & Wakefield
- The two firms count differently. Read each as a trend; don't add them.
Who is buying?
Foreigners take about one in seven condo units, and the mix is shifting.
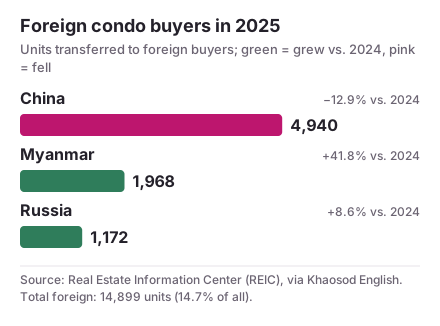
- 2025 total: 14,899 units (+2.2%) worth THB 60.92 billion (−10.7%). That is 14.7% of units and 25% of value. Khaosod English
- By value: China THB 18.59 bn (−30%), Myanmar 6.16 bn (−12.5%), Russia 4.77 bn (+30.3%).
- By province: Bangkok 7,029 units, Chonburi (incl. Pattaya) 4,164, Phuket 1,190.
- Where each group buys: Chinese in Bangkok, Chonburi and Chiang Mai; Myanmar buyers in Bangkok, Samut Prakan and Chiang Mai; Russians in Phuket, Chonburi and Prachuap Khiri Khan.
- No other nationality has fully filled the gap left by Chinese buyers. Cushman & Wakefield
About six in seven units go to non-foreign buyers, so the local market matters more.
Why can't local buyers absorb the stock? Bank credit more than rates
Interest rates fell in 2026. Loans did not get easier.
- Policy rate: cut from 1.25% to 1.00% on 25 February, held on 26 August by a unanimous vote. Thairath Bank of Thailand
- Before that: it rose from 0.5% to 2.5% in about a year after the pandemic. The Nation
- Retail loan rates barely moved. Banks cut their prime retail rate (MRR) by only 0.10–0.15 points. MRR is now 6.50% at Bangkok Bank, 6.58% at Kasikornbank, 6.845% at Krungthai and 6.145% at the Government Housing Bank. It is a benchmark, not your rate. Thairath
- Banks are rationing credit. Lending by major institutions fell about 2.1% in Q1, while pawnshop lending rose 18.3%. Household debt fell to 85.9% of GDP, a six-year low, but SCB EIC calls it "constraint-driven deleveraging", not better finances. The Nation
- Demand is cooling. 56% of consumers plan no home purchase in five years, the survey's highest. Interest is shifting to homes at THB 3 million or less. Some renters have moved back in with family. The Nation
Rejection is highest for the cheapest homes.
- Developers reported average rejection of 40% (Q4 2024) and 45% (Q1 2025).
- By price in Q4 2024: THB 1–3 million, 65–70%; THB 3–7 million, 40%; THB 7 million and above, 15%.
- Top reasons: credit-bureau problems, high debt, unstable or undocumented income. Bangkok Post
- One association reported above 50% in October 2026. Pattaya Mail Different surveys and dates, so read it as a range.
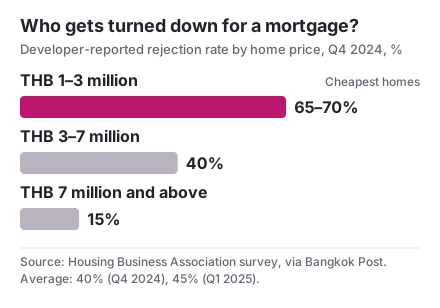
Inflation is moderate but rising into early 2027.
- September 2026: 2.82% headline, 1.50% core, mostly fuel and fresh food. The 2026 forecast is 1.8–2.2%. The Nation
- Bank of Thailand: expects inflation to rise through Q1 2027, then return to low levels. Household spending stays cautious. Bank of Thailand
- Risks: falling wages, fewer hours, higher unemployment. The Nation
- We found no source that measures how much a typical household's mortgage capacity has changed.
What do demographics add?
Smaller households and an older population are context, not proof of demand.
- Population: about 70.3 million in 2025, growing 0.42% (a record low). Average household size is 2.5, with more single-person homes and condo living. NSO via ASEAN Now
- Ageing: people aged 60+ rose from 6.8% of the population in 1994 to 20% in 2024. Bangkok Post
- Senior housing is thin: 916 projects at end-2024 (832 nursing homes, 84 residences), 516 in Bangkok and nearby. Occupancy: Bangkok nursing homes 69.2%, Bangkok residences 75.6%, Samut Prakan residences 70.9%. Private residences mostly cost THB 30,000–50,000 a month.
- We found no source that measures how much of the overhang these trends could absorb.
What help exists from the state?
Fee cuts help Thai owner-occupiers. Other schemes are narrow or have ended.
- Lower fees: transfer fee 2% → 0.01% and mortgage registration 1% → 0.01% until 30 June 2027. Price and loan must not exceed THB 7 million. Described as aimed at Thai individuals buying for their own use, so check eligibility. The Nation
- National Housing Authority: up to 20% off in 69 projects, with hire-purchase for people rejected by banks. It ended on 30 September 2026. Thairath
- Subsidised rental: 588 units in Bang Pakong, Chachoengsao at THB 1,500–2,100 a month for households earning up to THB 30,000. It is outside our three areas and shows the scale. Thairath
What does it mean for buyers?
Analysts expect a buyer's market for one to two years.
- Knight Frank expects more promotions. Recovery depends on interest rates, further easing and income growth. Knight Frank
- Developers are offering deep discounts, rent-to-own, longer payment plans, free transfers and years of free common fees. Pattaya Mail
Our own checklist, not from the sources:
- Ask how many units in the building are unsold or for sale. A large share usually means more room to negotiate.
- Get every incentive in writing: how long free fees run and who pays transfer costs.
- Compare resale and new-build prices in the same area.
- Foreign buyers: ask the developer for the building's remaining foreign quota before paying a deposit.
What is the outlook?
Cautious: a modest recovery, not a rebound.
- AREA expects about 5% recovery in 2026 and flat conditions in 2027–2029. Pattaya Mail
- H1 2026 transfers rose 17.6% to 167,665 homes, but buyers rushed to transfer before 30 June, so part of the rise may be timing.
- The Thai Real Estate Association expects gradual growth in 2027 and calls the market fragile. Pattaya Mail, 11 Oct 2026
Sources
- Pattaya Mail: Is Thailand's housing recovery real? (3 Feb 2026) · Uncertain recovery despite rising transfers (11 Oct 2026) · Condo market finds new ways to clear massive inventory (Jul 2026)
- The Nation: Worst slowdown in nearly 30 years (15 Jan 2026) · Household debt-to-GDP ratio falls · Five signs of a slow recovery (12 Sep 2026) · September inflation (Oct 2026) · 0.01% fee cut extended (30 Jun 2026)
- Knight Frank: Bangkok Condominium Market Q1 2026 · Cushman & Wakefield: Thailand real estate update 2026
- Khaosod English: China still tops Thai condo market (REIC data) (4 Mar 2026)
- Bank of Thailand: MPC decision 4/2026 · Thairath: bank rate cuts · Thairath: NHA campaign · Thairath: NHA rental
- Bangkok Post: mortgage rejection rates · Bangkok Post: senior housing · ASEAN Now: 2025 census
This article is general information, not financial or legal advice. Figures come from third-party reports as cited and may be revised.